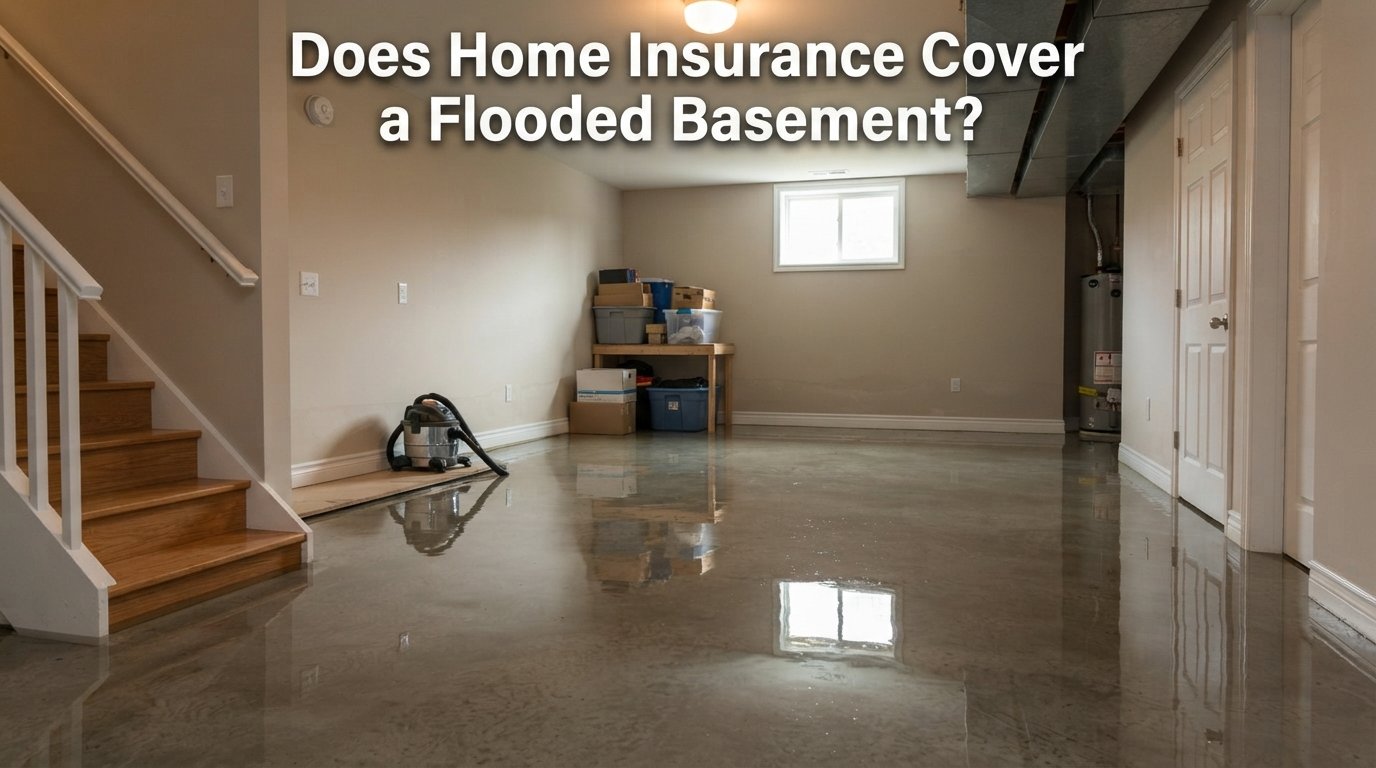

Home insurance covers a flooded basement only in certain situations, and the answer really depends on what caused the water to enter your home. If a pipe bursts inside your house or an appliance malfunctions, your standard policy usually pays for the damage.
But if the flooding comes from heavy rain, a rising river, or backed-up drains, your regular homeowners policy will most likely deny the claim. This is why so many homeowners get confused and later face unexpected repair bills. Understanding the difference between sudden internal water damage and external flooding is the key to knowing exactly where you stand.
Understanding How Homeowners Insurance Works
Homeowners insurance is built around a list of covered causes of loss, often called “perils.” If your basement flooding matches one of these listed perils, you are covered; if it does not, you are not.
What a Standard Policy Typically Covers
A standard homeowners policy usually covers sudden and accidental water damage happening from inside the home.
This includes things like a pipe suddenly breaking, a washing machine hose failing, or a water heater bursting without warning. The key word insurers focus on is “sudden,” meaning the damage must not have built up slowly over time.
Named Perils vs All-Risk Policies
Some policies list specific covered perils, known as named-peril policies, while others cover everything except what is specifically excluded, known as all-risk policies. All-risk policies generally offer broader protection, but even these almost always exclude flood damage from natural sources like storms or rising water.
Why the Cause of Damage Matters So Much
Insurance companies investigate the root cause of every water damage claim before approving or denying it. Two basements can look exactly the same after flooding, but one claim gets approved and the other gets rejected simply because of what triggered the water intrusion in the first place.
When Basement Flooding Is Covered by Insurance
In many cases, homeowners insurance does step in when the flooding happens suddenly and comes from a source inside the home rather than from outside weather events.
Burst or Frozen Pipes
If a pipe inside your home suddenly bursts or freezes and cracks open, releasing water into your basement, this is typically covered under a standard homeowners policy since it counts as sudden internal damage rather than gradual neglect.
Water Heater Malfunction
When a water heater fails unexpectedly and floods the surrounding area, insurers generally treat this as an accidental, sudden event. As long as the appliance was properly maintained, the resulting basement damage is usually eligible for a claim.
Accidental Appliance Overflow
Washing machines, dishwashers, and other water-using appliances can occasionally overflow due to mechanical failure. This type of sudden accidental discharge is commonly covered, provided it wasn’t caused by long-term neglect of the appliance.
HVAC System Leaks
Heating and cooling systems located in or near the basement sometimes develop sudden leaks. If this happens unexpectedly, the resulting water damage to your basement is often covered under your existing policy.
When Basement Flooding Is Not Covered
This is where most homeowners get caught off guard, because natural and external water sources are almost always excluded from standard coverage.
Heavy Rain and Storm Runoff
When heavy rainfall causes water to seep through basement walls or foundation cracks from the outside, this is classified as flood damage, not water damage, and standard homeowners insurance will not cover it.
Flash Floods and Rising Water Bodies
If a nearby river, lake, or storm drain overflows and floods your basement, this is a textbook flood event. Regular home insurance policies universally exclude this type of damage, regardless of how much destruction it causes.
Sewer and Drain Backups
Water or sewage backing up through drains or sump systems into your basement is excluded by default in almost every standard policy, unless you have purchased a specific backup endorsement.
Poor Maintenance and Neglect
If an insurer determines that the flooding happened because you failed to maintain your plumbing, foundation, or sump pump properly, they can deny the claim entirely, even if the damage looks accidental.
The Role of Flood Insurance
Since standard policies leave such a large gap, flood insurance exists specifically to cover the water damage scenarios that homeowners insurance ignores.
What the National Flood Insurance Program Covers
The NFIP, run through FEMA in the United States, offers flood coverage for structural damage and certain belongings when flooding results from natural events like storms, overflowing rivers, or rapid snowmelt.
Private Flood Insurance Alternatives
Beyond the NFIP, several private insurers now offer flood insurance policies that can sometimes provide higher coverage limits or faster claims processing, giving homeowners more flexible options depending on their location and risk level.
Who Actually Needs Flood Insurance
Homes located in designated flood zones are often required by mortgage lenders to carry flood insurance, but even homes outside these zones can experience flooding, so many advisors recommend at least considering a policy regardless of zone classification.
Sewer and Sump Pump Backup Coverage
Because sewer backups are so common yet excluded by default, insurers offer this protection as an add-on rather than a standard inclusion.
Why This Coverage Is Excluded by Default
Insurers treat sewer backup as a maintenance-related and localized risk rather than a sudden accidental event, which is why it sits outside standard policy language and requires a separate endorsement to be included.
Cost and Value of Adding This Endorsement
This endorsement is usually inexpensive compared to the potential repair costs of a sewage-related basement flood, making it one of the more cost-effective additions homeowners can make to their existing policy.
How to Check Your Own Policy
Rather than assuming your coverage status, it’s always safer to physically review your policy documents or speak directly with your insurance provider.
Key Terms to Look For
Look specifically for terms like “water damage,” “flood exclusion,” “sewer backup,” and “sump pump failure” within your policy’s declarations and exclusions sections to understand exactly where your coverage begins and ends.
Questions to Ask Your Insurance Agent
Ask your agent directly whether flood, sewer backup, and sump pump failure are included, and request written confirmation so you have clear documentation of your actual coverage scope.
Steps to Take After a Flooded Basement
Acting quickly and correctly after discovering a flooded basement can significantly affect how smoothly your claim, if applicable, gets processed.
Safety and Damage Documentation
Turn off electricity to the affected area if it’s safe to do so, avoid contact with standing water, and thoroughly photograph and video the damage before starting any cleanup so you have solid evidence for your insurer.
Contacting Your Insurer and Preventing Further Damage
Report the incident to your insurance company as soon as possible, and take reasonable steps like removing standing water or using fans to prevent the damage from worsening while you wait for an adjuster.
How to Prevent Basement Flooding
Prevention is almost always cheaper than dealing with a claim, denied or approved, so taking proactive steps matters.
| Prevention Method | What It Does |
| Sump pump with battery backup | Removes water even during power outages |
| Proper yard grading | Directs rainwater away from the foundation |
| Foundation crack sealing | Blocks water from seeping through walls |
| Gutter and downspout maintenance | Prevents overflow near the foundation |
| Regular plumbing inspection | Catches leaks before they become major floods |
Cost Considerations
Understanding the financial side helps homeowners decide whether additional coverage is worth the investment.
Average Claim Payouts and Deductibles
Water damage claims can range widely depending on severity, and most policies apply a specific deductible for water-related claims that homeowners should confirm in advance rather than discovering during a stressful claim process.
Is Add-On Coverage Worth It
Given that flood and sewer backup damage can cost thousands of dollars to repair, the relatively small added premium for these endorsements is generally considered a smart investment for most homeowners.
Frequently Asked Questions
Does renters insurance cover a flooded basement?
Renters insurance typically covers personal belongings damaged by sudden internal water events but excludes flood damage just like homeowners policies.
Will filing a claim raise my premium?
Yes, filing a water damage claim can often lead to a premium increase at your next renewal, depending on your insurer and claims history.
What’s the difference between water damage and flood damage?
Water damage usually refers to sudden internal issues like burst pipes, while flood damage refers to external natural water sources like storms or rising rivers.
Can I buy flood insurance if I’m not in a flood zone?
Yes, flood insurance is available to homeowners outside official flood zones, and many choose to purchase it as extra protection.
Conclusion
So, does home insurance cover a flooded basement? The honest answer is that it depends entirely on the cause.
Sudden internal issues like burst pipes or appliance failures are usually covered, while external flooding from storms, rivers, or sewer backups typically is not, unless you’ve added specific endorsements. Reviewing your policy now and adding flood or sewer backup coverage where needed can save you from a painful surprise later.
Related Articles
486 Gelney Kitchen Exhaust Hood System: How It Works and Why It Matters
How to Clean Linoleum Floors: Complete Care Guide 2026
How Do You Remove Glue From Hardwood Floors? A Complete Step-by-Step Guide
How to Strip Floors: A Complete Step-by-Step Guide for Every Floor Type